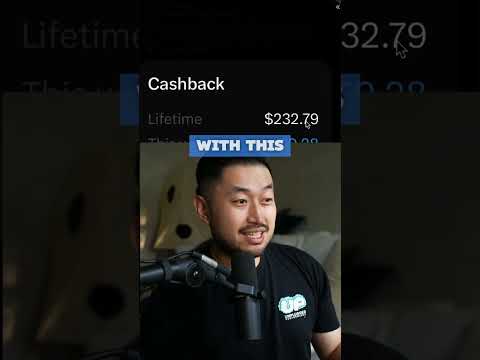
XMoney slashing 3% cashback on everyday purchases like groceries and utilities has wiped out up to $2,500 yearly for heavy users, which is why I cancelled my XMoney card.
XMoney Card Changes Hit Hard
The recent xmoney card changes targeted core cashback categories, eliminating rewards on utilities, warehouse clubs, jewelry stores, insurance premiums, and colleges. This directly explains the surge in "cancelled xmoney card cashback" searches as people wake up to zero rewards on routine spending.
From the transcript details, these xmoney cashback categories were stripped retroactively, leaving users frustrated after big purchases. My own family grocery runs no longer earn anything, turning what felt like a smart fintech tool into an ordinary debit card.
Why Cancel XMoney Card Now
The biggest pain point is how xmoney rewards removed value from high-volume categories without warning. When rewards vanish on the stuff you buy most, the card loses its edge fast. I weighed the lost 3% against alternatives and realized sticking around made zero sense.
Counterpoint on Interest Rates
To be fair, XMoney did expand access to 4-6% interest without needing the premium subscription anymore. That improvement helps some users and shows the company is still iterating. Yet better rates on savings cannot offset losing cashback on real-world expenses that add up quickly.
If you want to explore the updated interest option, check this breakdown: https://denniscw.com/blog/xmoney-6-interest-without-subscription-now-available
My Final Take
After running the numbers on lost rewards versus any remaining perks, cancelling was the only logical move. The xmoney card changes turned a once-useful card into something I no longer recommend.
Watch the full story in the video here: https://youtube.com/watch?v=0nRodkScjTQ
For more on the exact reasons behind my decision, read the companion post: https://denniscw.com/blog/xmoney-card-cashback-removed-why-cancelled
Some links are affiliate links that support the channel at no cost to you.